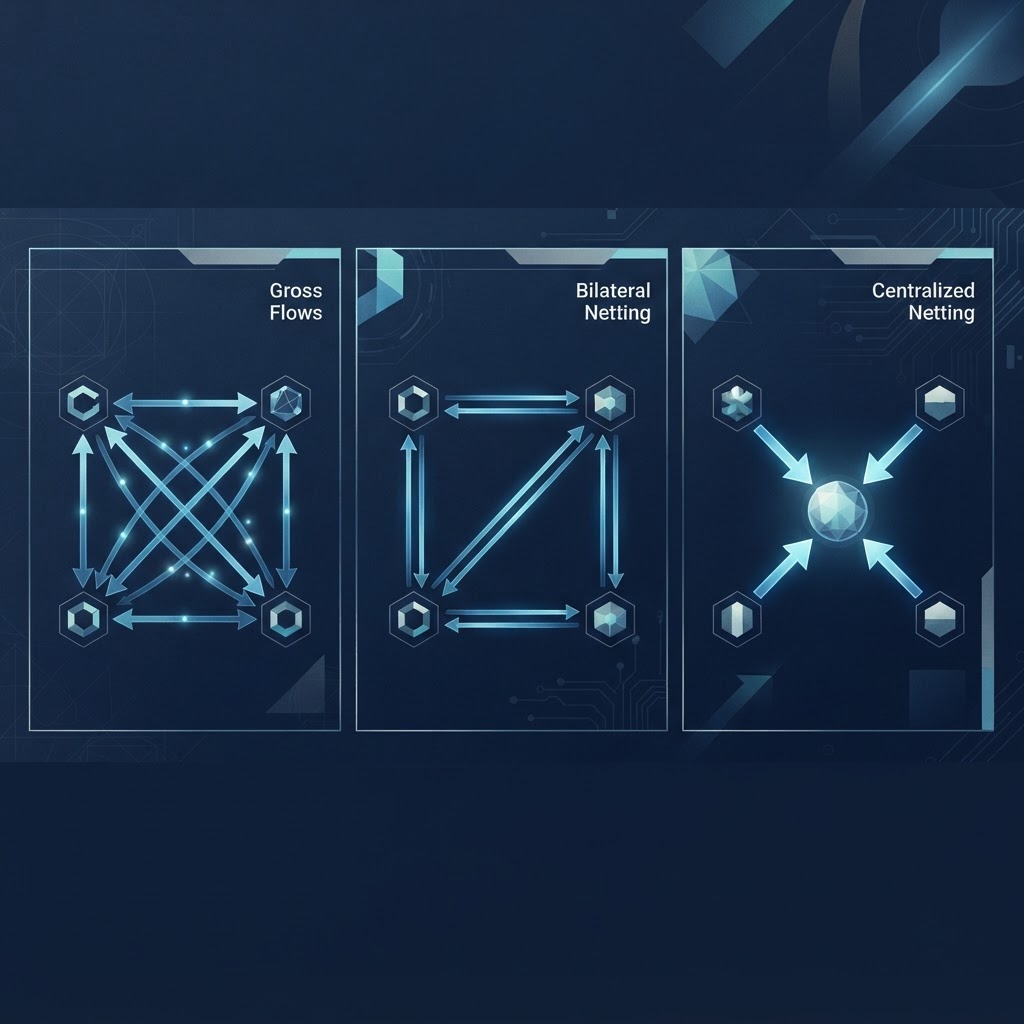
The bilateral vs multilateral netting question usually comes up when the intercompany invoices get annoying. Two subsidiaries keep paying each other in opposite directions, someone suggests offsetting them, and a month later the CFO asks whether the group should "do proper netting". Most answers online stop at two definitions. That tells you what the words mean. It does not tell you which one fits a group of three, eight or fifteen entities, what each costs to run, or why your bank's ISDA uses the same words for something legally different.
This guide answers those three things. The numbers come from one illustrative four-entity group, the same one we work through line by line in our worked multilateral netting example, so you can check every figure. If you want the concept first, read our guide to multilateral netting.
The short answer
Bilateral netting offsets what two entities owe each other, so each pair settles one net amount. Multilateral netting offsets what every entity owes every other entity at once, so each entity settles one net amount with a central netting centre.
Treasury Today puts the operational difference plainly: in bilateral netting no netting centre is involved and payments still need to be made via the external banking system where fees will be charged, while in multilateral netting a single centre acts as counterparty to every subsidiary and no payments move except to or from it.
The practical rule most treasury writers converge on: bilateral netting reduces transaction count between those two parties but does nothing for the rest of the group, and multilateral is the standard once three or more subsidiaries trade with each other regularly.
Side by side on one set of numbers
Take four entities: UK Ltd (GBP, the parent), DE GmbH (EUR), FR SAS (EUR) and PL sp. z o.o. (PLN). In one illustrative month they raise 12 intercompany invoices worth 635,000 GBP equivalent. Every entity owes every other one something, which is the worst case: with four entities, 12 directional flows.
Bilateral: one net payment per pair
Four entities form six pairs. Bilateral netting nets each pair against itself. UK owes DE 120 and DE owes UK 90, so UK pays DE 30. Repeat for the other five pairs and the month settles with 6 payments and 135,000 GBP of value. Half the payments, a fifth of the value.
What bilateral netting cannot see is that DE's surplus against PL and its deficit against FR are part of one position. Each pair is netted in isolation.
Multilateral: one net payment per entity
Multilateral netting adds up each entity's receipts minus its payments across the whole group. DE is a net receiver of 35. UK, FR and PL are net payers of 5, 5 and 25. The positions sum to zero, which is the check every run must pass. The month settles with 3 payments and 35,000 GBP of value.
Same invoices, same month. Twelve payments gross, six bilateral, three multilateral. When we price every leg in the worked example, including the netting centre's own legs and the FX margin, the illustrative monthly settlement cost goes from about 4,531 GBP gross to about 958 GBP bilateral to about 288 GBP multilateral with currency accounts. The FX margin, not the wire fee, is most of the difference.
Comparison table
| Bilateral netting | Multilateral netting | |
|---|---|---|
| Who offsets | Two entities | All participating entities at once |
| Counterparty | The other entity | The netting centre |
| Payments left | Up to one per pair: n(n-1)/2 | Up to one per entity: n |
| Central function | None | Group treasury, in-house bank or treasury subsidiary |
| FX | Each pair converts its own net | Centre converts net currency positions for the group |
| Setup | Low, often an offset in the ERP | Cycle calendar, policy, netting agreement, usually software |
| Who runs it | Accounts payable and receivable | Treasury with accounting |
| Best fit | Two entities, or a few pairs with two-way trade | Three or more entities, several currencies, monthly volume |
The FX row matters more than it looks. In a multilateral scheme, Treasury Today notes, the FX rates for all disbursements are typically set by the netting centre, so the group converts each currency once, on the net, instead of every pair paying a bank spread on its own leg.
When bilateral netting is enough
Bilateral netting is not a lesser product. For many small groups it is the right one.
- •Two entities. With one pair, bilateral and multilateral netting give the same answer. A netting centre adds work and saves nothing.
- •Few pairs with two-way trade. If a parent and two subsidiaries invoice each other, but the subsidiaries never invoice each other, most of the benefit sits in the two parent pairs.
- •One currency. If every entity runs in the same currency, there is no FX margin to save, only payment fees.
- •No appetite for a cycle. Offsetting receivables and payables with one business partner inside the ERP is effectively bilateral netting. It needs no calendar, no cut-off and no central owner.
The weakness is scale. Payments after bilateral netting can grow with the number of pairs, n(n-1)/2. Six entities make 15 pairs; ten make 45. Multilateral netting caps it at one payment per entity, so ten entities settle in at most 10 payments, not 45.
When to move to multilateral
The signal is not group size alone. It is three things together: three or more entities invoicing in more than one direction, more than one operating currency, and a monthly rhythm stable enough to set a cut-off date.
Expect the move to be an accounting project as much as a treasury one. The BELLIN interview in Treasury Management International describes multilateral netting as the evolution of bilateral netting, with group treasury running a netting centre that acts as a reconciliation hub, and stresses that treasury needs accounting on board because the cycle starts with reconciling every intercompany invoice.
Two things do not change when you switch:
- •Every invoice still settles in the books. Only the cash movement shrinks. Each entity still records its intercompany payables and receivables in full.
- •Reporting can stay gross. In Germany, the Bundesbank is explicit that for netting the gross amounts are reported as incoming and outgoing payments. This applies to bilateral and multilateral netting alike, so a German subsidiary keeps its gross data either way.
Some jurisdictions restrict or condition net settlement. Groups usually handle those entities by settling them gross, or bilaterally, outside the multilateral cycle. Check each entity's position with an adviser. This article is general information, not legal, tax or treasury advice.
What the terms mean in FX and derivatives
If your group trades FX forwards or derivatives with banks, you will meet "bilateral netting" again in the documentation, where it means something narrower and legal.
Payment, novation and close-out netting
The New York Fed's Foreign Exchange Committee splits bilateral settlement netting into two forms, payment netting or novation netting, often combined with close-out netting in master agreements:
- •Payment netting combines amounts due on the same day in the same currency into one payment. This is the closest relative of corporate bilateral netting.
- •Novation netting replaces matching contracts with a single new net contract.
- •Close-out netting applies only when one party defaults: all outstanding contracts are terminated, valued and collapsed into one amount owed one way.
The same guide notes that the ISDA Master Agreement contains optional payment netting provisions but does not provide for novation netting, and that local counsel opinions are obtained on whether netting survives a counterparty's insolvency.
Why multilateral close-out netting is rare
In markets, "multilateral netting" usually means a clearinghouse or central counterparty. The RBA describes how a central counterparty becomes the buyer to every seller and the seller to every buyer through novation, replacing many bilateral exposures with one. Legally, that turns a multilateral arrangement back into a set of bilateral ones. UNIDROIT's netting principles say exactly that: central clearing breaks down into bilateral relationships, and truly multilateral close-out netting is not as common as bilateral netting because insolvency law has to accept offsetting claims that lack mutuality.
Why a corporate finance lead should care: a group netting centre also sits between the subsidiaries, and the netting agreement is what makes each subsidiary's obligation run to the centre rather than to its sister company. Write that down in a signed group netting agreement. Do not leave it as a spreadsheet convention.
Where an account layer fits
Neither form of netting removes the settlement step. It shrinks it. The cheapest settlement is a transfer that never leaves the group's own account structure, and that is the part an account layer can do.
When each entity holds its currency balances on one platform, the netting centre can collect and pay out in the original currency and convert only the net. Our published pricing is the reference point we use: UK Faster Payments and SEPA at 0.99 GBP, SWIFT at 26.40 GBP, FX from 0.70 percent on major pairs, internal transfers free, and dedicated IBANs across 16 or more currencies. Rates elsewhere will differ, and the method in the worked example works with any of them. For the wider picture of money moving between your own companies, read our guide to intercompany payments.
An account layer does not calculate net positions, reconcile disputed invoices or file your Bundesbank reports. Netting calculations sit in your ERP, a spreadsheet or currency netting software; the setup, cycle and accounting entries for groups are covered in multilateral intercompany netting.
The compliance position, stated exactly. Regulated payment services are provided by Gemba Finance Limited, FCA FRN 804853, UK customers only. EXFI is a trading name of EX Financial Solutions Ltd, which is not itself authorised or regulated by the FCA and acts as a distributor of those services. These are payment accounts, not bank accounts; funds are not covered by the FSCS but are safeguarded in segregated accounts in accordance with the Payment Services Regulations 2017.
FAQ
Is bilateral netting the same as set-off? Close, but not identical. Set-off is the legal right to offset mutual claims between the same two parties. Bilateral netting is the agreed process of doing it routinely, by payment date or by contract. In markets, close-out netting is the version that applies on default, and its enforceability depends on the governing law.
Can a group run bilateral and multilateral netting at the same time? Yes, and many do. Entities in jurisdictions that restrict net settlement are often left out of the multilateral cycle and settle gross or pair by pair, while the rest of the group nets through the centre.
Does multilateral netting need special software? Not at first. A group of three or four entities can run a monthly cycle in a spreadsheet with a fixed cut-off and a zero-sum check. Dedicated netting modules or a treasury management system pay off as entities, currencies and disputes grow.
Who is the counterparty in multilateral netting? The netting centre. Each subsidiary pays the centre if it is a net payer or receives from the centre if it is a net receiver. Subsidiaries stop paying each other directly for the invoices in the cycle.